
Everybody's waiting for mortgage rates to come down. But two things already changed in Florida that can lower your monthly payment about as much as a full point off your rate, and you don't have to wait on the Fed to get them.
I'm Juan Rodriguez, Your Florida Home Coach. Here's what changed, what the math looks like on a typical Wesley Chapel home, and how to make sure you actually get the savings.
1. Florida insurance rates are coming down
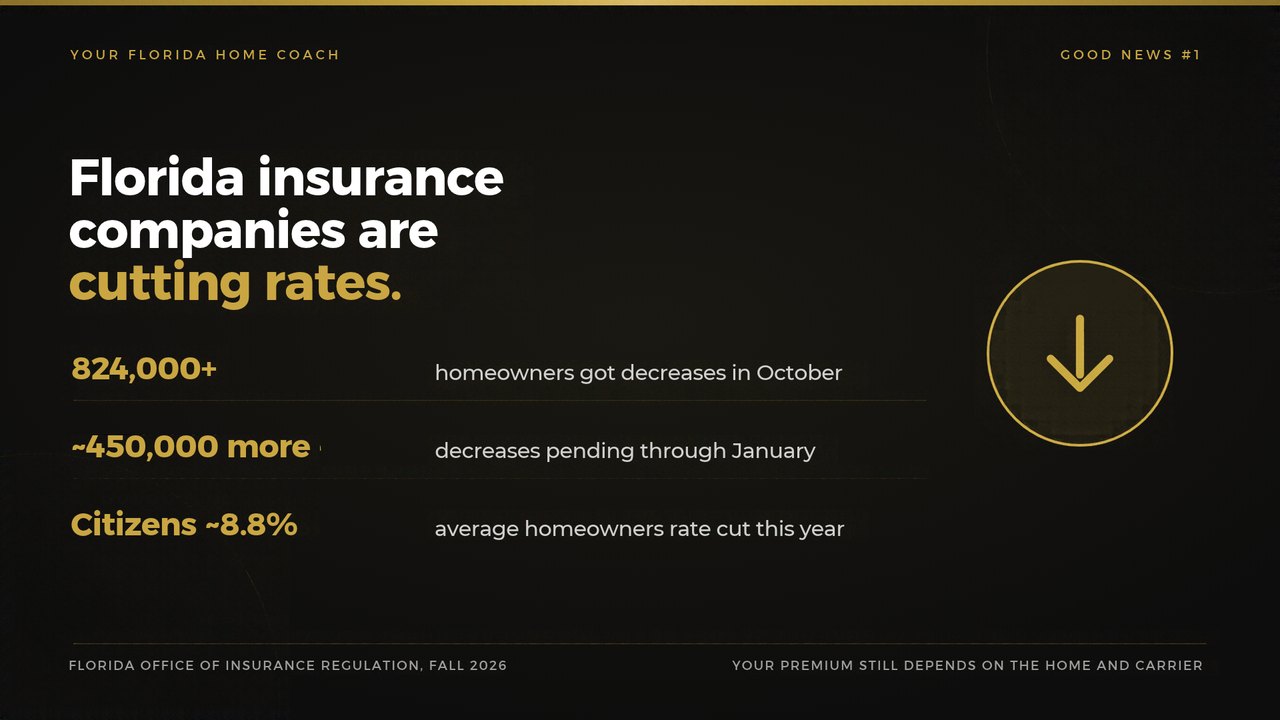
For the last few years, insurance was the line item that broke a lot of Florida budgets. That's changing.
- At the end of October, Florida's Office of Insurance Regulation said more than 824,000 homeowners were getting rate decreases that month, some as large as 12 percent.
- About 450,000 more decreases are on the way through January.
- Since January 2024, 48 companies have filed for decreases.
- Citizens cut its average homeowners rate 8.8 percent this year.
Not every policy goes down. Your premium still depends on the home, the roof and the carrier. But for the first time in a while, the market is moving in the buyer's favor.
2. Amendment 3: a much bigger homestead exemption
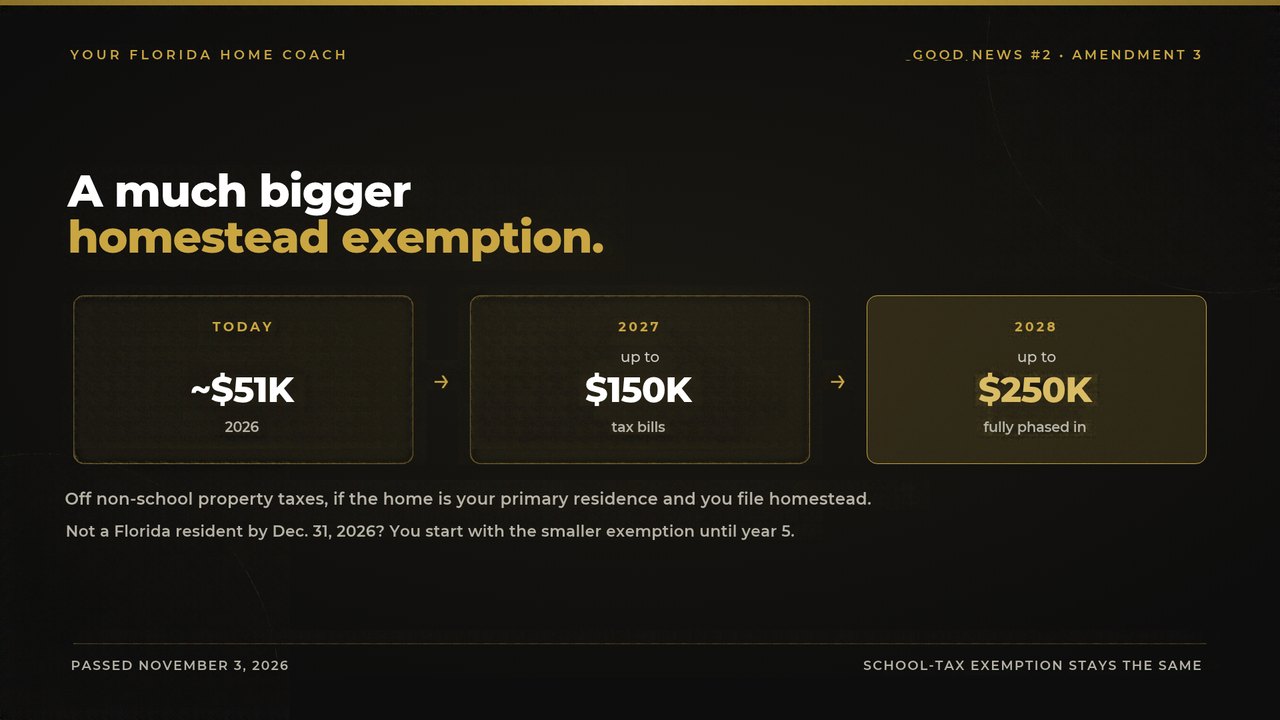
On November 3, Florida voters passed Amendment 3. If the home is your primary residence and you file for homestead:
- Starting with 2027 tax bills, you can exempt up to $150,000 of assessed value from non-school property taxes.
- In 2028, that rises to $250,000.
- Today it's about $51,000. The $25,000 school-tax exemption stays the same.
- Save Our Homes still applies: after your first year, your assessed value can't rise more than 3 percent or inflation, whichever is lower.
One important catch: if you're not a Florida resident by December 31, 2026, you start with the smaller exemption and become eligible for the bigger one in your fifth year. If you're planning a move to Florida, that date matters. (I'm a Realtor, not a tax advisor, so confirm your situation with your county property appraiser.)
3. The math: almost a 1-point rate drop
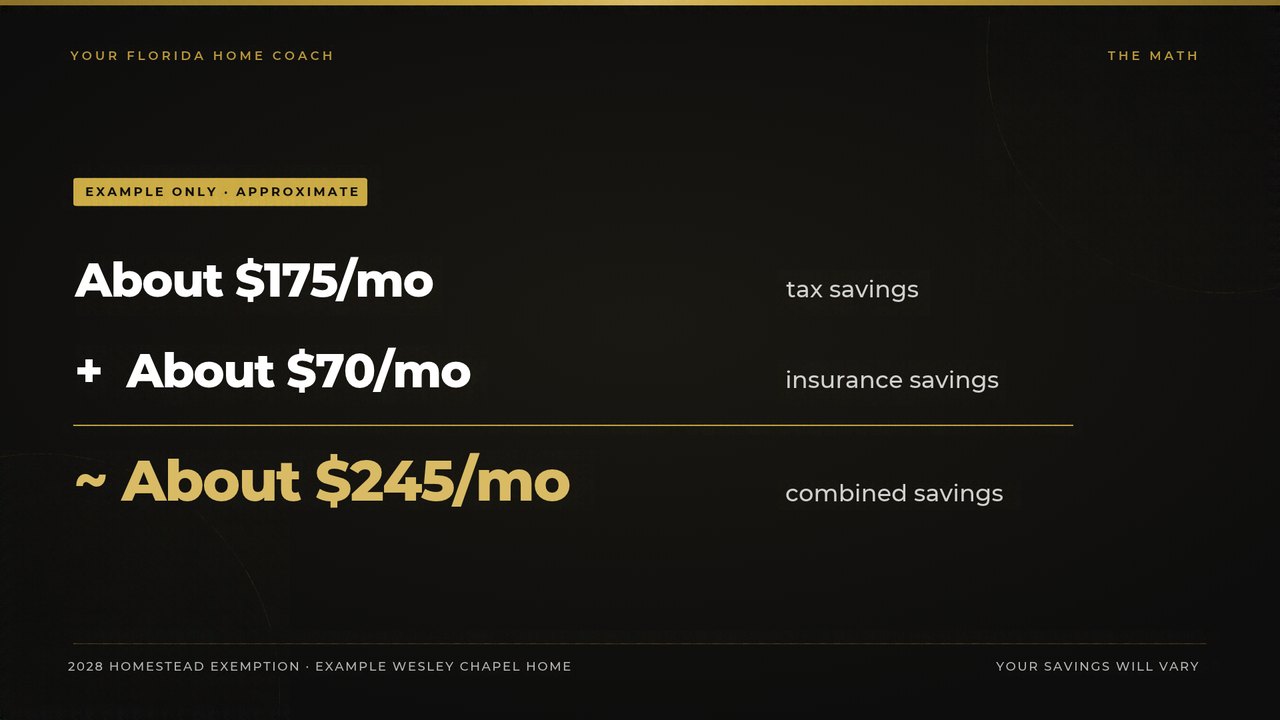
This is a clearly labeled example, not a quote.
| Example assumption | Figure |
|---|---|
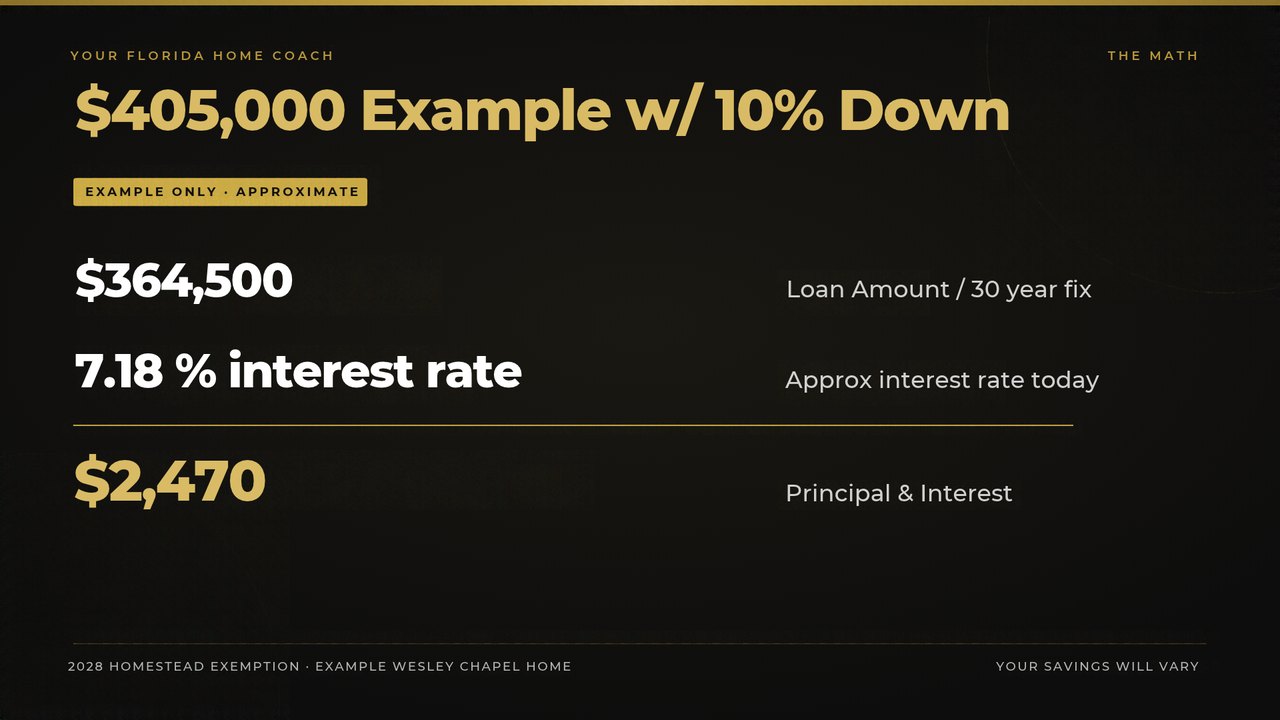
| Home price (about the Wesley Chapel median) | $405,000 |
| Down payment | 10% |
| Loan, 30-year fixed | $364,500 |
| Principal and interest at 7.18% | about $2,470/mo |
| Principal and interest at 6.18% | about $2,230/mo |
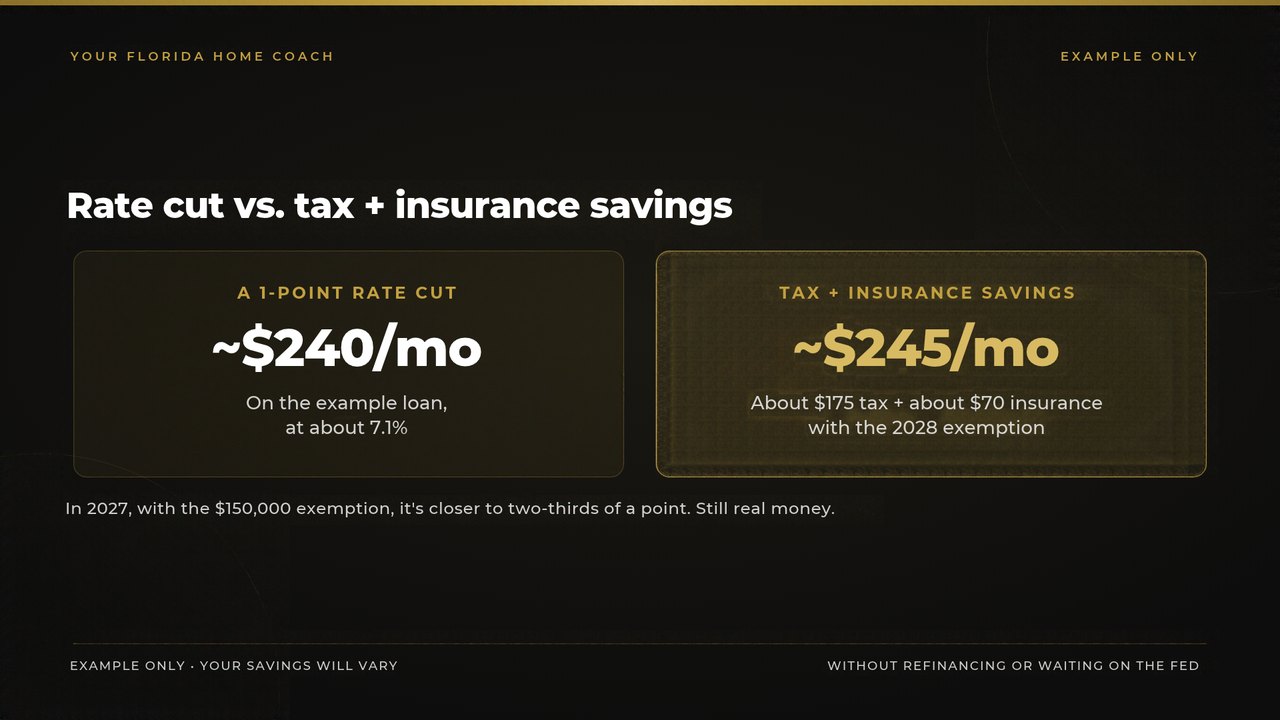
| Value of one full point | about $240/mo |
Now the savings side:
- Taxes: in unincorporated Pasco, non-school taxes run about 10.5 mills. Once the $250,000 exemption is fully in place in 2028, that's roughly $2,100 a year, or about $175 a month, if tax rates stay the same.
- Insurance: if a newer home with good wind-mitigation features saves you even $70 a month compared with what you'd have paid before, you're at about $245 a month total.
That's almost exactly a 1-point rate drop, without refinancing. In 2027, with the $150,000 exemption, it's closer to two-thirds of a point. Still real money.
Example only: $405K price, 10% down, 30-year fixed, unincorporated Pasco at 10.5 non-school mills, 2028 exemption, tax rates unchanged, homestead qualified. CDD fees are separate and not affected. Your numbers will differ.
4. How to actually get the savings
The savings don't happen automatically. Here's what we do together:
- File homestead. You need to own and live in the home by January 1 and apply by March 1.
- Get a wind mitigation inspection. Roof shape, roof-to-wall connections, and impact windows or shutters can unlock real discounts.
- Shop insurance on the actual address before you write the offer, not after.
- Negotiate. With homes sitting longer right now, there may be room for seller credits toward a rate buydown or closing costs. That's my job: I advise you, negotiate the deal and manage it all the way to closing.
A quick note for investors
Homestead doesn't apply to rentals. But Amendment 3 also cuts the cap on non-homestead assessment increases from 10 percent to 5 percent, so your tax bill should be more predictable, and lower insurance helps cash flow too.
Want me to run the numbers on a home you like?
If you're thinking about buying or selling in Wesley Chapel, New Tampa, Land O' Lakes, Lutz, Zephyrhills or Tampa, call or text me at 813-438-6170 or reach out at urflahome.com. Watch the full breakdown on my YouTube channel, Your Florida Home Coach: https://www.youtube.com/@YourFloridaHomeCoach
This is general information, not insurance, tax, legal or lending advice. Confirm quotes with a licensed insurance agent and lender, and tax questions with your county property appraiser or a tax professional.
Juan Rodriguez, Realtor | eXp Realty, LLC | License SL3439563 | Your Florida Home Coach | Equal Housing Opportunity
Sources: Florida OIR press release Oct 29, 2026; Citizens 2026 rate release; Florida DOR bulletin PTO 26-21 (Nov 5, 2026); Freddie Mac PMMS; Pasco Property Appraiser 2026 millage.